Accounting For Decision MakingUnit 910 min read
Cost Estimation & Cost Behavior: Types, Analysis & Applications
Unit 9 of Accounting For Decision Making covers cost estimation techniques (engineering, account analysis, high-low method), cost behavior analysis (fixed vs variable vs mixed costs), cost-volume-profit relationships, and real-world applications in Nepali businesses like Daraz, Ncell, and local manufacturing firms. Inc
TAKEAWAYS:
- Cost estimation predicts future costs using historical data or engineering calculations, while cost behavior analysis classifies costs as fixed, variable, or mixed to aid decision-making.
- The high-low method isolates variable costs by comparing the highest and lowest activity levels, while account analysis relies on managerial judgment to classify costs.
- Cost-volume-profit (CVP) analysis uses the equation Profit = (P × Q) – (V × Q) – F to determine break-even points, target profits, or sales volumes.
- Mixed costs require separation into fixed and variable components (e.g., using scatter plots or regression) before analysis.
- Nepali businesses like Daraz (delivery costs) and Ncell (customer service costs) use cost behavior analysis to optimize pricing and resource allocation.
- Exam focus: Numerical problems (e.g., calculating break-even units, predicting costs at new output levels) and conceptual questions (e.g., differences between cost estimation methods).
1. Cost Estimation: Methods and Applications
Cost estimation predicts future costs based on historical data or engineering standards. It is critical for budgeting, pricing, and decision-making in businesses like eSewa (transaction fees) or Khalti (payment processing costs).
Key Methods of Cost Estimation
| Method | Description | Example in Nepal |
|---|---|---|
| Engineering Method | Uses detailed analysis of production processes to estimate costs. | A Kathmandu furniture manufacturer estimates wood, labor, and machinery costs per chair. |
| Account Analysis | Classifies costs as fixed or variable based on account ledgers. | NTC classifies salaries (fixed) vs. fuel costs (variable) for bus operations. |
| High-Low Method | Isolates variable cost using the highest and lowest activity levels. | Pathao estimates driver wages (variable) vs. app maintenance (fixed) costs. |
| Least Squares Regression | Statistically fits a cost line to data points for accuracy. | Nepal Rastra Bank predicts inflation-related costs using economic data. |
flowchart TD
    A["Cost Estimation Methods"] --> B["Engineering Method"]
    A --> C["Account Analysis"]
    A --> D["High-Low Method"]
    A --> E["Regression Analysis"]
    B --> F["Detailed Process Breakdown"]
    C --> G["Ledger Classification"]
    D --> H["Highest/Lowest Activity Points"]
    E --> I["Statistical Cost Line"]
Worked Example: High-Low Method for a Nepali Bakery
Scenario: Sweet Delight Bakery (Kathmandu) provides the following data for 2023:
| Month | Units Sold | Total Cost (Rs) |
|---|---|---|
| January | 5,000 | 80,000 |
| February | 8,000 | 100,000 |
| March | 3,000 | 70,000 |
Step 1: Identify the highest (February: 8,000 units, Rs 100,000) and lowest (March: 3,000 units, Rs 70,000) activity levels. Step 2: Calculate the variable cost per unit: Step 3: Calculate the fixed cost using the high point: Step 4: Formulate the cost equation: Prediction: If Sweet Delight sells 6,000 units in April:
2. Cost Behavior Analysis: Fixed, Variable, and Mixed Costs
Cost behavior refers to how costs react to changes in activity levels (e.g., units produced, sales volume). Classifying costs correctly is essential for pricing, budgeting, and break-even analysis.
Types of Costs
| Type | Definition | Example in Nepal | Graphical Representation |
|---|---|---|---|
| Fixed Cost | Remains constant regardless of activity level. | Ncell’s monthly rent for a call center (Rs 500,000). | Horizontal line. |
| Variable Cost | Changes proportionally with activity level. | Daraz’s delivery charges (Rs 100 per order). | Straight line from origin. |
| Mixed Cost | Contains both fixed and variable components. | NTC’s bus fuel costs (fixed maintenance + variable diesel). | Line with y-intercept (fixed) and slope (variable). |
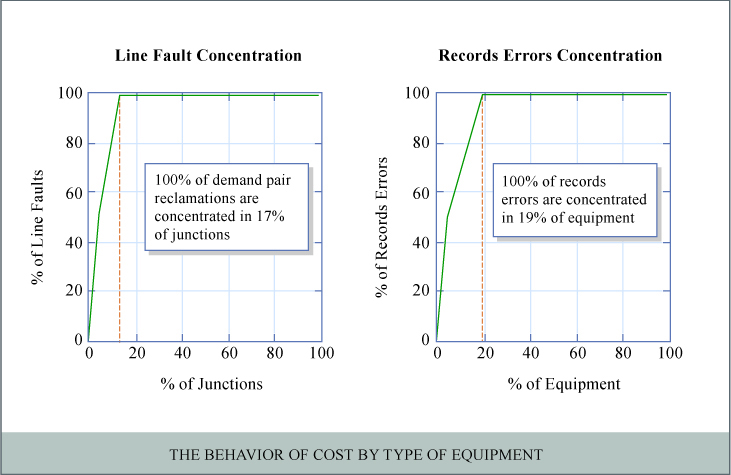 cost behavior graph (Image: mitopencourseware, CC BY-SA 4.0, via Wikimedia Commons)
graph LR
    A["Total Cost"] --> B["Fixed Cost\n(Rs 50,000)"]
    A --> C["Variable Cost\n(Rs 5 × Units)"]
    B --> D["Horizontal Line"]
    C --> E["Sloped Line"]
    F["Mixed Cost = Fixed + Variable"] --> G["Line with Y-intercept"]
Separating Mixed Costs: Scatter Plot Method
Example: Himalayan Textiles (Pokhara) has the following data for electricity costs:
| Month | Machinery Hours | Electricity Cost (Rs) |
|---|---|---|
| January | 1,000 | 40,000 |
| February | 1,500 | 50,000 |
| March | 2,000 | 60,000 |
Steps:
- Plot the data points on a graph (Machinery Hours on X-axis, Electricity Cost on Y-axis).
- Draw a best-fit line (visually or using regression).
- The y-intercept = Fixed Cost (e.g., Rs 20,000).
- The slope = Variable Cost per hour (e.g., Rs 20/hour).
Cost Equation:
3. Cost-Volume-Profit (CVP) Analysis
CVP analysis examines how changes in costs and volume affect profits. It uses the contribution margin (Sales – Variable Costs) to cover fixed costs and generate profit.
Key Formulas
- Contribution Margin (CM):
- Break-Even Point (Units):
- Profit Target:
graph TD
    A["Sales Revenue\n(Sloped Line)"]
    B["Total Costs\n(Fixed + Variable)"]
    C["Break-Even Point\n(Where A = B)"]
    D["Profit Area\n(A > B)"]
    E["Loss Area\n(A < B)"]
    A --> C
    B --> C
Worked Example: Break-Even for a Kathmandu Retail Shop
Scenario: Kathmandu Electronics sells smartphones with:
- Selling Price (P): Rs 50,000
- Variable Cost per Unit (V): Rs 30,000 (including purchase cost and delivery)
- Fixed Costs (F): Rs 2,000,000 (rent, salaries, marketing)
- Desired Profit: Rs 500,000
Step 1: Calculate Contribution Margin (CM):
Step 2: Calculate Break-Even Units:
Step 3: Calculate Sales for Desired Profit:
Interpretation:
- The shop must sell 100 units to cover costs.
- To earn Rs 500,000 profit, it needs 125 units.
- Margin of Safety: Current sales (150 units) – Break-even (100 units) = 50 units.
4. Real-World Applications in Nepal
Case 1: Daraz (E-Commerce Pricing)
- Cost Behavior: Daraz’s delivery costs are mixed:
- Fixed: Warehouse rent, app maintenance.
- Variable: Fuel, driver wages (per order).
- Application: Daraz uses high-low method to estimate variable delivery costs and sets dynamic pricing (e.g., Rs 100 for local orders, Rs 500 for remote areas).
Case 2: Ncell (Telecom Cost Control)
- Cost Behavior: Customer service costs are mixed:
- Fixed: Call center salaries, software licenses.
- Variable: Per-call charges, overtime pay.
- Application: Ncell uses CVP analysis to determine the minimum number of calls needed to cover fixed costs before profit.
Case 3: Local Manufacturing (e.g., Brick Kilns)
- Cost Estimation: A brick kiln in Bhaktapur estimates:
- Fixed Costs: Land lease (Rs 50,000/month), manager’s salary (Rs 30,000).
- Variable Costs: Clay (Rs 2/kg), fuel (Rs 5/batch), labor (Rs 100/worker).
- Break-Even: If each brick costs Rs 10 to produce and sells for Rs 15, the kiln needs to sell 10,000 bricks/month to break even: (Note: Adjust for actual data.)
5. Exam Tip: How to Score Full Marks
Numerical Problems:
- Always show all steps (e.g., high-low method calculations).
- Label fixed and variable components clearly.
- Use realistic units (e.g., "per unit," "per month").
Conceptual Questions:
- Define terms precisely (e.g., "Fixed costs are those that do not change with the level of output within a relevant range.").
- Compare methods in tables (e.g., engineering vs. account analysis).
Diagrams:
- Draw CVP graphs with labeled axes (e.g., "Sales Revenue," "Total Cost").
- Use t-accounts for cost allocation (e.g., separating manufacturing vs. administrative costs).
Real-World Links:
- Relate answers to Nepali businesses (e.g., "Like Daraz, local retailers can use break-even analysis to set minimum order quantities.").
Final Checklist for Exams: ✅ Can you classify costs as fixed/variable/mixed? ✅ Can you calculate break-even using the formula? ✅ Can you estimate costs using high-low or account analysis? ✅ Can you draw a CVP graph with profit/loss areas? ✅ Can you apply concepts to a Nepali business scenario?
Based on the TU BBM syllabus for Accounting For Decision Making (ACC313), unit 9.
Discussion
Loading…