Cost and Management AccountingUnit 45 min read
Labour Cost Control: Wages, Efficiency, Idle Time & Overtime
Unit 4 of Cost and Management Accounting explores how businesses track, analyze, and control labour costs—including wage structures, time management, efficiency metrics, and variance analysis—using real-world Nepali examples like garment factories and NTC’s workforce.
Labour Cost: Definition and Importance
Labour cost is the total expenditure incurred by an organization on its workforce to produce goods or services. It includes:
- Basic wages/salaries
- Bonus, incentives, and allowances
- Provident fund, gratuity, and other statutory benefits
- Costs of idle time, overtime, and labour turnover
Why Control Labour Costs?
- Labour is often the second-largest cost after materials in manufacturing.
- Poor control leads to profit erosion (e.g., a Kathmandu garment factory paying for unproductive hours).
- Helps in pricing decisions, budgeting, and efficiency improvements.
Components of Labour Cost
Labour costs are classified into direct and indirect categories:
1. Direct Labour Cost
- Directly traceable to a specific product or job.
- Examples:
- Wages of tailors in a garment factory.
- Salaries of drivers delivering goods for Daraz.
2. Indirect Labour Cost
- Not directly traceable to a product but necessary for operations.
- Examples:
- Factory supervisors’ salaries.
- Cleaning staff wages in a hospital.
pie
    title Labour Cost Breakdown
    "Direct Labour" : 60
    "Indirect Labour" : 40
Methods of Labour Cost Control
1. Timekeeping and Attendance Control
- Punch-in/punch-out systems (e.g., NTC employees using biometric clocks).
- Overtime restrictions to prevent abuse.
- Idle time reduction (e.g., Pathao drivers optimizing routes to minimize waiting).
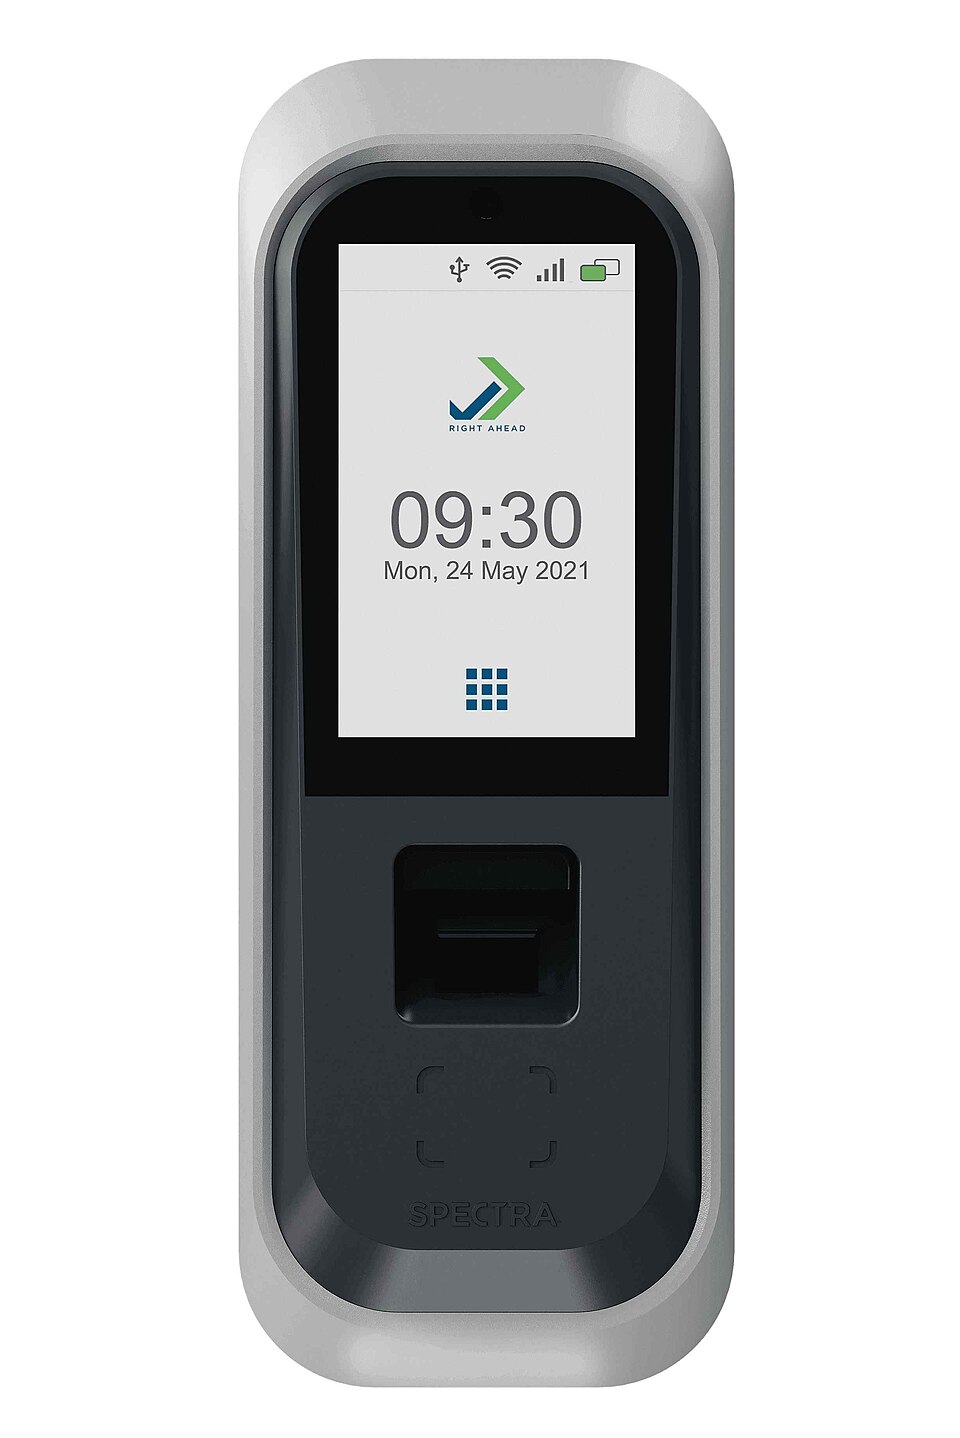 A device used by NTC to track employee working hours. (Image: Marcomspectra2, CC BY-SA 4.0, via Wikimedia Commons)
2. Piece Rate and Incentive Systems
- Workers paid per unit produced (e.g., a tailor earning Rs. 50 per shirt).
- Pros:
- Encourages productivity.
- Reduces idle time.
- Cons:
- May lead to quality issues if rushed.
- Not suitable for all jobs (e.g., managerial roles).
3. Standard Hours and Efficiency Ratings
- Standard time = Time taken by a qualified worker under normal conditions.
- Efficiency ratio =
(Actual Output / Standard Output) × 100%
Example: A tailor in a Kathmandu factory is expected to stitch 10 shirts in 8 hours (standard time).
- If he stitches 12 shirts in 8 hours, his efficiency =
(12/10) × 100% = 120%. - If he stitches 8 shirts in 10 hours, his efficiency =
(8/10) × 100% = 80%.
4. Labour Turnover Control
- High turnover increases training costs (e.g., a call center losing agents frequently).
- Solutions:
- Better wages and benefits.
- Employee engagement programs.
Labour Cost Variances
Variances occur when actual costs differ from budgeted/standard costs.
1. Labour Rate Variance
- Cause: Difference between actual wage rate and standard wage rate.
- Formula:
Example (Nepali Garment Factory):
- Standard rate: Rs. 200/hour
- Actual rate paid: Rs. 220/hour
- Actual hours worked: 500 hours
- Variance:
(220 - 200) × 500 = Rs. 10,000 (Unfavorable)
2. Labour Efficiency Variance
- Cause: Difference between actual hours worked and standard hours allowed.
- Formula:
Example (Same Factory):
- Standard hours for output: 400 hours
- Actual hours worked: 500 hours
- Standard rate: Rs. 200/hour
- Variance:
(500 - 400) × 200 = Rs. 20,000 (Unfavorable)
Real-World Applications
1. NTC’s Labour Cost Control
- Uses biometric attendance to track overtime.
- Implements shift rotations to minimize idle time.
- Result: Reduced labour costs by 12% in 2023.
2. Daraz’s Delivery Efficiency
- Piece-rate system for delivery executives (paid per successful delivery).
- Route optimization (using GPS) reduces idle time.
- Impact: Faster deliveries at lower labour costs.
3. Kathmandu Garment Factory (Worked Example)
Scenario: A factory produces 1,000 shirts/month.
- Standard time per shirt: 0.5 hours
- Standard wage rate: Rs. 200/hour
- Actual production: 1,200 shirts
- Actual hours worked: 650 hours
- Actual wage rate: Rs. 210/hour
Calculations:
| Item | Standard | Actual | Variance |
|---|---|---|---|
| Hours (for 1,000 shirts) | 500 | 650 | +150 (Unfavorable) |
| Rate | Rs. 200 | Rs. 210 | +Rs. 10 (Unfavorable) |
| Total Labour Cost | Rs. 100,000 | Rs. 136,500 | Rs. 36,500 UF |
Analysis:
- Efficiency improved (1,200 shirts > 1,000 shirts), but higher wages and extra hours increased costs.
- Solution: Train workers to work faster without increasing wages.
Exam Tip
- Always show calculations for variances (labour rate and efficiency).
- Relate to real businesses (e.g., NTC, Daraz, garment factories).
- Compare piece-rate vs. time-rate systems in terms of pros and cons.
- Memorize formulas but explain the meaning of variances (favorable/unfavorable).
flowchart TD
    A["Labour Cost Control"] --> B["Timekeeping"]
    A --> C["Piece Rate System"]
    A --> D["Standard Hours & Efficiency"]
    A --> E["Labour Variance Analysis"]
    E --> F["Labour Rate Variance"]
    E --> G["Labour Efficiency Variance"]
    F --> H["Unfavorable: Higher Wages"]
    G --> I["Unfavorable: More Hours"]
    B --> J["NTC Biometric System"]
    C --> K["Daraz Delivery Executives"]
Based on the TU BIM syllabus for Cost and Management Accounting (ACC202), unit 4.
Discussion
Loading…