Financial ManagementUnit 47 min read
Capital Budgeting: NPV, IRR, Payback, and Decision Rules
Unit 4 of Financial Management: This note explains the process of capital budgeting, the key evaluation techniques such as NPV, IRR, Payback Period, and Profitability Index, and how to apply them in real Nepali business scenarios.
Key points
- Capital budgeting is the systematic process of evaluating long‑term investment projects.
- Net Present Value (NPV) is the most reliable decision rule because it measures value added in monetary terms.
- Internal Rate of Return (IRR) is useful for comparing projects of different sizes but can give multiple or misleading results.
- Payback Period and Discounted Payback provide quick, though less accurate, measures of liquidity and risk.
- Sensitivity, scenario, and real‑options analysis extend basic NPV to account for uncertainty.
- Proper capital budgeting aligns investment decisions with a firm’s cost of capital and strategic objectives.
Capital Budgeting Overview
Capital budgeting is the discipline of planning, evaluating, and selecting long‑term investment projects that will generate cash flows over multiple years. It is the bridge between a firm’s strategic objectives and its financial resources.
The Capital Budgeting Process
flowchart TD
  A["Identify Investment Opportunities"] --> B["Estimate Cash Flows"]
  B --> C["Determine Discount Rate"]
  C --> D["Compute NPV, IRR, Payback, PI"]
  D --> E["Perform Sensitivity & Scenario Analysis"]
  E --> F["Make Decision: Accept or Reject"]
  F --> G["Implement & Monitor"]
Key Concepts and Definitions
| Term | Definition |
|---|---|
| Cash Flow | Net inflow or outflow of cash attributable to a project. |
| Discount Rate | The rate used to convert future cash flows into present value; usually the firm’s weighted average cost of capital (WACC). |
| Net Present Value (NPV) | Sum of discounted cash flows minus initial investment. |
| Internal Rate of Return (IRR) | Discount rate that makes NPV zero. |
| Payback Period | Time required to recover the initial investment from cumulative cash inflows. |
| Discounted Payback Period | Payback period calculated using discounted cash flows. |
| Profitability Index (PI) | Ratio of the present value of future cash flows to the initial investment. |
| Sensitivity Analysis | Examining how changes in key assumptions affect NPV or IRR. |
| Scenario Analysis | Evaluating NPV under different sets of assumptions (best, base, worst). |
| Real Options | Optionality embedded in projects (e.g., expand, abandon, delay). |
Cash Flow Estimation
Cash flows are divided into initial outlay and operating cash flows.
- Initial Outlay: Purchase of assets, installation costs, working capital changes.
- Operating Cash Flows:
- Terminal Cash Flow: Salvage value plus release of working capital at project end.
Example: Kathmandu Retail Shop – New POS System
| Year | Cash Flow (NPR) |
|---|---|
| 0 (Initial) | 1,200,000 (POS purchase + installation) |
| 1 | 300,000 |
| 2 | 350,000 |
| 3 | 400,000 |
| 4 | 450,000 |
| 5 | 500,000 + 200,000 (salvage) = 700,000 |
Assume WACC = 12 % and tax rate = 30 %. Depreciation is straight‑line over 5 years: 240,000 per year.
Net Present Value (NPV)
NPV is calculated as:
where is the discount rate.
Calculations:
| Year | CF (NPR) | Discount Factor | Present Value (NPR) |
|---|---|---|---|
| 0 | 1.000 | ||
| 1 | 300,000 | 0.893 | 267,900 |
| 2 | 350,000 | 0.797 | 278,950 |
| 3 | 400,000 | 0.711 | 284,400 |
| 4 | 450,000 | 0.635 | 285,750 |
| 5 | 700,000 | 0.567 | 396,900 |
| NPV | + 413,000 |
Since NPV > 0, the POS investment adds value and should be accepted.
Internal Rate of Return (IRR)
IRR is the discount rate that sets NPV to zero. It can be found by trial‑and‑error or using financial calculators.
For the POS example, IRR ≈ 18 %.
- Interpretation: The project yields an 18 % return per year, higher than the 12 % WACC.
- Decision Rule: Accept if IRR ≥ WACC.
Payback Period
Payback Period = time to recover initial investment from cumulative cash inflows.
| Year | Cash Flow | Cumulative CF |
|---|---|---|
| 0 | ||
| 1 | 300,000 | |
| 2 | 350,000 | |
| 3 | 400,000 | |
| 4 | 450,000 | 300,000 |
Payback = 3 years + (150,000/450,000) ≈ 3.33 years.
Discounted Payback Period
Using discounted cash flows:
| Year | Discounted CF | Cumulative Discounted CF |
|---|---|---|
| 0 | ||
| 1 | 267,900 | |
| 2 | 278,950 | |
| 3 | 284,400 | |
| 4 | 285,750 | |
| 5 | 396,900 | 313,901 |
Discounted Payback ≈ 4.5 years.
Profitability Index (PI)
PI = 1.34.
Rule: Accept if PI > 1.
Comparison of Decision Rules
| Rule | Decision Criterion | Strength | Weakness |
|---|---|---|---|
| NPV | NPV > 0 | Measures absolute value added | Requires accurate discount rate |
| IRR | IRR ≥ WACC | Easy to interpret | Multiple IRRs, ignores scale |
| Payback | Payback ≤ Target | Simple, liquidity focus | Ignores time value of money |
| Discounted Payback | Discounted Payback ≤ Target | Considers time value | Still ignores cash flows after payback |
| PI | PI > 1 | Useful for capital rationing | Sensitive to discount rate |
Sensitivity and Scenario Analysis
- Sensitivity: Vary one variable (e.g., sales volume) and observe NPV change.
- Scenario: Define best, base, worst cases and compute NPVs for each.
flowchart LR
  A["Base Case NPV"] --> B["Best Case NPV"]
  A --> C["Worst Case NPV"]
  B --> D["Decision"]
  C --> D
Real Options in Capital Budgeting
Projects often contain optionality: the ability to expand, abandon, or delay. Real‑options valuation (e.g., Black‑Scholes) can be applied to capture this value, especially in volatile markets like Nepal’s telecom sector.
In the Real World
eSewa – Payment Gateway Upgrade
- Uses NPV to evaluate the cost of adding new security features.
- Discount rate set at 10 % (WACC).
- Projected cash inflows from increased transaction volume yield an NPV of NPR + 2 million, justifying the upgrade.
Daraz – New Warehouse Construction
- Applies IRR to compare multiple warehouse sites.
- Site A: IRR = 15 % (WACC = 12 %); Site B: IRR = 10 %.
- Daraz selects Site A despite higher cost because IRR exceeds WACC.
Ncell – 5G Rollout
- Uses Discounted Payback to ensure the investment recovers within 4 years, aligning with regulatory timelines.
- Payback period of 3.8 years meets the company’s risk appetite.
Worked Example – Kathmandu Retail Shop
Problem: A shop wants to replace its aging cash register with a modern POS system.
- Initial cost: NPR 1,200,000.
- Expected annual savings: NPR 300,000, increasing by NPR 50,000 each year.
- Salvage value after 5 years: NPR 200,000.
- WACC: 12 %.
Solution:
- Build cash flow table (shown above).
- Compute NPV (shown above) → NPR + 413,000.
- Compute IRR → 18 %.
- Payback → 3.33 years.
- Discounted Payback → 4.5 years.
- PI → 1.34.
Decision: Accept the investment (NPV > 0, IRR > WACC, PI > 1).
Exam Tip
- Understand the decision rules: Know when to use NPV, IRR, Payback, PI.
- Practice cash flow tables: Be able to construct and discount cash flows quickly.
- Know the formulas: Memorize NPV, IRR, PI equations and how to set up the NPV equation for IRR.
- Interpret results: Explain why a project is accepted or rejected based on each metric.
- Sensitivity: Be ready to discuss how changes in discount rate or cash flows affect NPV.
 POS terminal used in retail shops (Image: VideoPlasty, CC BY-SA 4.0, via Wikimedia Commons)
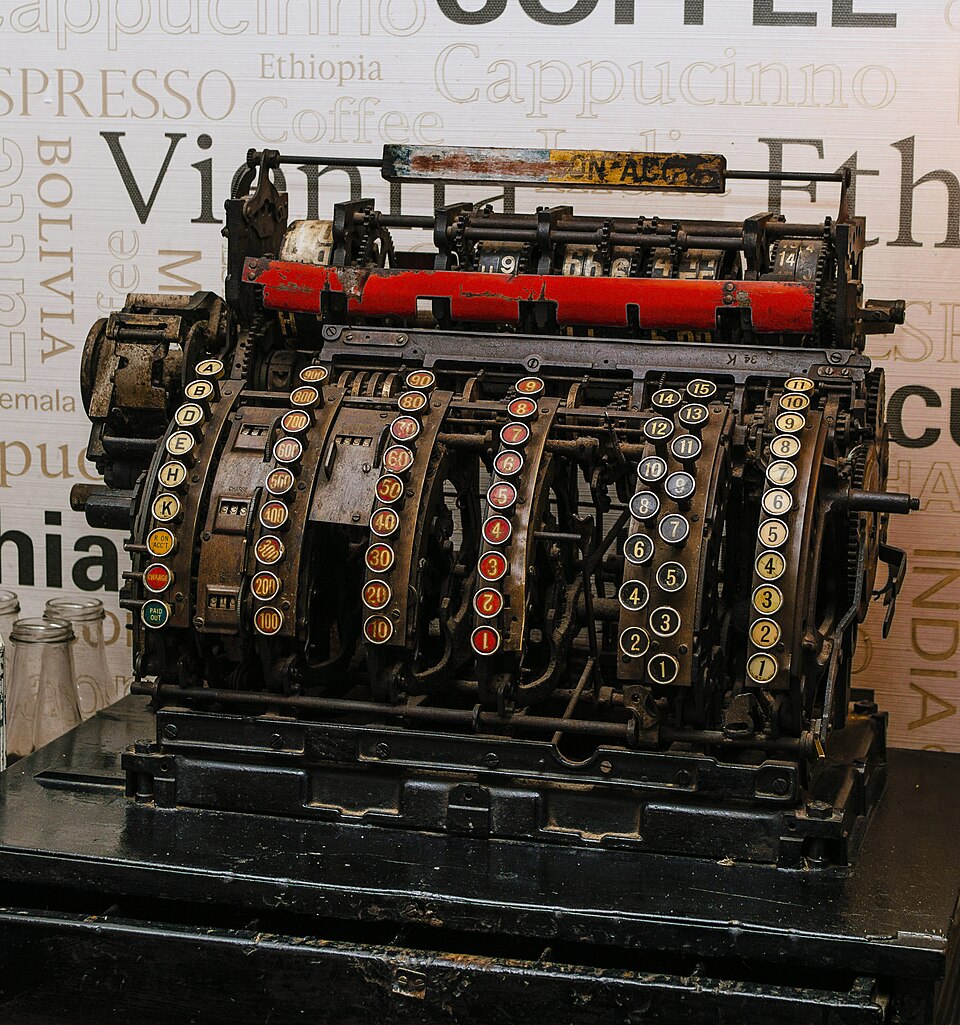 Traditional cash register in a Nepali shop (Image: Subhrajyoti07, CC BY-SA 4.0, via Wikimedia Commons)
Based on the PU BBA (PU) syllabus for Financial Management, unit 4.
Discussion
Loading…