Tourism and Hospitality AccountingUnit 811 min read
Travel Agency Accounting: Transactions, Ledgers & Statements
Unit 8 of Tourism and Hospitality Accounting covers specialized accounting for travel agencies, including unique transactions (commission, refunds, advance payments), ledger postings for travel services, and preparation of final accounts tailored to tourism businesses. Learn how to handle foreign exchange, tour operato
Key Concepts in Travel Agency Accounting
1. Unique Transactions in Travel Agencies
Travel agencies deal with transactions that are uncommon in other businesses. These include:
- Commission Income: Earned from tour operators, airlines, and hotels for booking services.
- Advance Payments (Deposits): Received from customers for future tours or services.
- Refunds: Given to customers for cancellations or changes.
- Foreign Exchange Transactions: Handling payments in foreign currencies (e.g., USD, EUR) for international tours.
- Tour Operator Settlements: Reconciling payments with tour operators for group tours.
How These Transactions Work
- Commission Income: When a travel agency books a flight or hotel for a customer, it earns a commission (e.g., 5-10% of the ticket price). This is recorded as income.
- Advance Payments: Customers pay in advance for tours. These are recorded as liabilities (money owed to customers) until the service is rendered.
- Refunds: If a customer cancels, the agency refunds the advance payment (or part of it) and adjusts the liability.
- Foreign Exchange: If a customer pays in NPR but the tour costs in USD, the agency must convert currencies and record exchange gains/losses.
2. Journal Entries for Travel Agency Transactions
Journal entries for travel agencies follow standard accounting rules but include unique accounts like Commission Income, Tour Operator A/c, and Foreign Exchange A/c.
Example 1: Recording Commission Income
Suppose Adventure Tours Nepal books a flight for a customer and earns a 10% commission of Rs. 50,000.
| Date       | Particulars                          | L.F. | Dr (Rs.) | Cr (Rs.) |
|------------|--------------------------------------|------|----------|----------|
| 2024-05-01 | Commission A/c Dr.                  |      | 50,000   |          |
|            | To Airline Commission A/c (50,000)  |      |          | 50,000   |
Explanation:
- The agency earns Rs. 50,000 as commission.
- This increases the agency’s revenue (Cr side of Commission A/c).
- The Airline Commission A/c is a liability until paid to the airline.
Example 2: Recording Advance Payments
A customer pays Rs. 20,000 in advance for a tour.
| Date       | Particulars                          | L.F. | Dr (Rs.) | Cr (Rs.) |
|------------|--------------------------------------|------|----------|----------|
| 2024-05-02 | Bank A/c Dr.                         |      | 20,000   |          |
|            | To Advance from Customers A/c (20,000)|      |          | 20,000   |
Explanation:
- The agency receives Rs. 20,000 in advance.
- This is a liability (money owed to the customer) until the tour is completed.
Example 3: Recording a Refund
If the customer cancels and the agency refunds Rs. 10,000, the entry is:
| Date       | Particulars                          | L.F. | Dr (Rs.) | Cr (Rs.) |
|------------|--------------------------------------|------|----------|----------|
| 2024-05-05 | Advance from Customers A/c Dr.       |      | 10,000   |          |
|            | To Bank A/c (10,000)                |      |          | 10,000   |
Explanation:
- The liability (Advance from Customers) decreases by Rs. 10,000.
- The agency pays Rs. 10,000 back to the customer.
3. Ledger Accounts for Travel Agencies
Ledger accounts in travel agencies include:
- Commission Income A/c (Revenue account)
- Tour Operator A/c (Asset/Liability account)
- Advance from Customers A/c (Liability account)
- Foreign Exchange A/c (Profit/Loss account)
Example: Ledger for Commission Income
Suppose Adventure Tours Nepal earns commissions over three months:
| Date       | Particulars                          | L.F. | Dr (Rs.) | Cr (Rs.) |
|------------|--------------------------------------|------|----------|----------|
| 2024-05-01 | To Airline Commission A/c            |      |          | 50,000   |
| 2024-06-01 | To Hotel Commission A/c             |      |          | 30,000   |
| 2024-07-01 | To Tour Operator Commission A/c     |      |          | 40,000   |
| **Total**  |                                      |      | **120,000** |          |
Balance: Rs. 120,000 Cr. (Income increases profit)
4. Foreign Exchange Transactions
Travel agencies often deal with foreign currencies. Exchange gains/losses must be recorded.
Example: Converting USD to NPR
Suppose Adventure Tours Nepal receives $1,000 from a customer for an international tour. The exchange rate is Rs. 120 = $1.
| Date       | Particulars                          | L.F. | Dr (Rs.) | Cr (Rs.) |
|------------|--------------------------------------|------|----------|----------|
| 2024-05-03 | Bank A/c Dr.                         |      | 120,000  |          |
|            | To Foreign Exchange A/c (Gain)      |      |          | 120,000  |
If the rate changes later (e.g., Rs. 125 = $1), a loss occurs:
| Date       | Particulars                          | L.F. | Dr (Rs.) | Cr (Rs.) |
|------------|--------------------------------------|------|----------|----------|
| 2024-06-03 | Foreign Exchange A/c (Loss) Dr.     |      | 5,000    |          |
|            | To Bank A/c (5,000)                 |      |          | 5,000    |
Explanation:
- Gain: When NPR strengthens (more NPR per USD).
- Loss: When NPR weakens (less NPR per USD).
5. Final Accounts for Travel Agencies
Final accounts include:
- Profit and Loss A/c (shows net profit/loss)
- Balance Sheet (shows assets, liabilities, and equity)
Example: Profit and Loss Account for Adventure Tours Nepal (for 3 months)
Assume:
- Commission Income: Rs. 120,000
- Expenses:
- Office Rent: Rs. 20,000
- Salaries: Rs. 30,000
- Foreign Exchange Loss: Rs. 5,000
- Miscellaneous: Rs. 5,000
| Particulars                          | Amount (Rs.) |
|--------------------------------------|--------------|
| **Income**                           |              |
| Commission Income                    | 120,000      |
| **Less: Expenses**                   |              |
| Office Rent                          | (20,000)     |
| Salaries                             | (30,000)     |
| Foreign Exchange Loss                | (5,000)      |
| Miscellaneous                        | (5,000)      |
| **Net Profit**                       | **60,000**   |
Balance Sheet (Simplified)
Assume:
- Assets: Cash at Bank (Rs. 80,000), Prepaid Expenses (Rs. 10,000)
- Liabilities: Advance from Customers (Rs. 10,000), Outstanding Expenses (Rs. 5,000)
- Equity: Capital (Rs. 155,000)
| **Liabilities & Equity**             | Amount (Rs.) | **Assets**               | Amount (Rs.) |
|--------------------------------------|--------------|---------------------------|--------------|
| Advance from Customers                | 10,000       | Cash at Bank              | 80,000       |
| Outstanding Expenses                 | 5,000        | Prepaid Expenses          | 10,000       |
| Capital                              | 155,000      | **Total Assets**          | **90,000**   |
| **Total Liabilities & Equity**       | **170,000**  |                           |              |
Note: The balance sheet must balance (Assets = Liabilities + Equity).
In the Real World
Travel agency accounting is critical for businesses like:
- eSewa (Nepal) – Handles advance payments for bus tickets and records commissions from transport companies.
- Pathao (Nepal/Global) – Manages driver commissions and refunds for cancelled rides.
- Daraz Travel (Nepal) – Records foreign exchange transactions for international bookings and settles commissions with hotels and airlines.
Worked Example: Kathmandu Travels (Nepali Business) Suppose Kathmandu Travels books a group tour to Pokhara for 20 customers at Rs. 5,000 per person. The tour operator charges a 10% commission, and customers pay 50% in advance.
Advance Payment from Customers:
- 20 customers × Rs. 2,500 (50% of Rs. 5,000) = Rs. 50,000
| Date       | Particulars                          | Dr (Rs.) | Cr (Rs.) |
|------------|--------------------------------------|----------|----------|
| 2024-05-01 | Bank A/c                             | 50,000   |          |
|            | To Advance from Customers A/c        |          | 50,000   |
Commission Paid to Tour Operator:
- Total tour cost: 20 × Rs. 5,000 = Rs. 100,000
- Commission (10%): Rs. 10,000
| Date       | Particulars                          | Dr (Rs.) | Cr (Rs.) |
|------------|--------------------------------------|----------|----------|
| 2024-05-02 | Tour Operator Commission A/c         | 10,000   |          |
|            | To Bank A/c                         |          | 10,000   |
Final Settlement:
- After the tour, the remaining Rs. 50,000 is collected from customers.
- The agency pays the tour operator Rs. 90,000 (Rs. 100,000 - Rs. 10,000 commission).
- Net profit: Rs. 10,000 (commission).
The Accounting Cycle for Travel Agencies
flowchart TD
    A["Start: Transactions Occur"] --> B["Record in Journal"]
    B --> C["Post to Ledger"]
    C --> D["Prepare Trial Balance"]
    D --> E["Prepare Final Accounts<br/>(Profit & Loss + Balance Sheet)"]
    E --> F["Close Books<br/>(Transfer Net Profit to Capital)"]
    F --> A
Comparison Table: Travel Agency vs. General Accounting
| Feature | Travel Agency Accounting | General Accounting |
|---|---|---|
| Unique Transactions | Commission, advance payments, refunds, foreign exchange | Sales, purchases, salaries, rent |
| Key Accounts | Tour Operator A/c, Foreign Exchange A/c, Advance A/c | Trade Receivables, Trade Payables |
| Foreign Exchange | Common (international tours) | Rare (unless export/import business) |
| Final Accounts | Includes commission income, tour operator settlements | Includes sales revenue, cost of goods sold |
| Refund Handling | Frequent (customer cancellations) | Less common (returns, discounts) |
Advantages and Disadvantages of Travel Agency Accounting
Advantages
✅ Clear Revenue Tracking: Commission income is easy to monitor. ✅ Better Cash Flow Management: Advance payments help plan expenses. ✅ Foreign Exchange Control: Helps manage currency risks. ✅ Customer Trust: Proper refund handling improves reputation.
Disadvantages
❌ Complexity in Foreign Exchange: Fluctuations can affect profits. ❌ High Refund Risks: Last-minute cancellations impact cash flow. ❌ Dependence on Tour Operators: Delays in settlements can cause issues. ❌ Regulatory Compliance: Must follow tourism board and tax rules.
Exam Tip
- Focus on Journal Entries: Always show Dr/Cr clearly for commission, advances, and refunds.
- Foreign Exchange: If given exchange rates, calculate gains/losses carefully.
- Final Accounts: Remember to include commission income in the Profit and Loss A/c and advances in the Balance Sheet under liabilities.
- Real-World Application: Relate answers to eSewa, Pathao, or Daraz if asked about commissions or refunds.
- Trial Balance: Ensure debits = credits before preparing final accounts.
- Common Mistakes to Avoid:
- Treating advances as income (they are liabilities).
- Ignoring foreign exchange fluctuations.
- Forgetting to close commission accounts in final accounts.
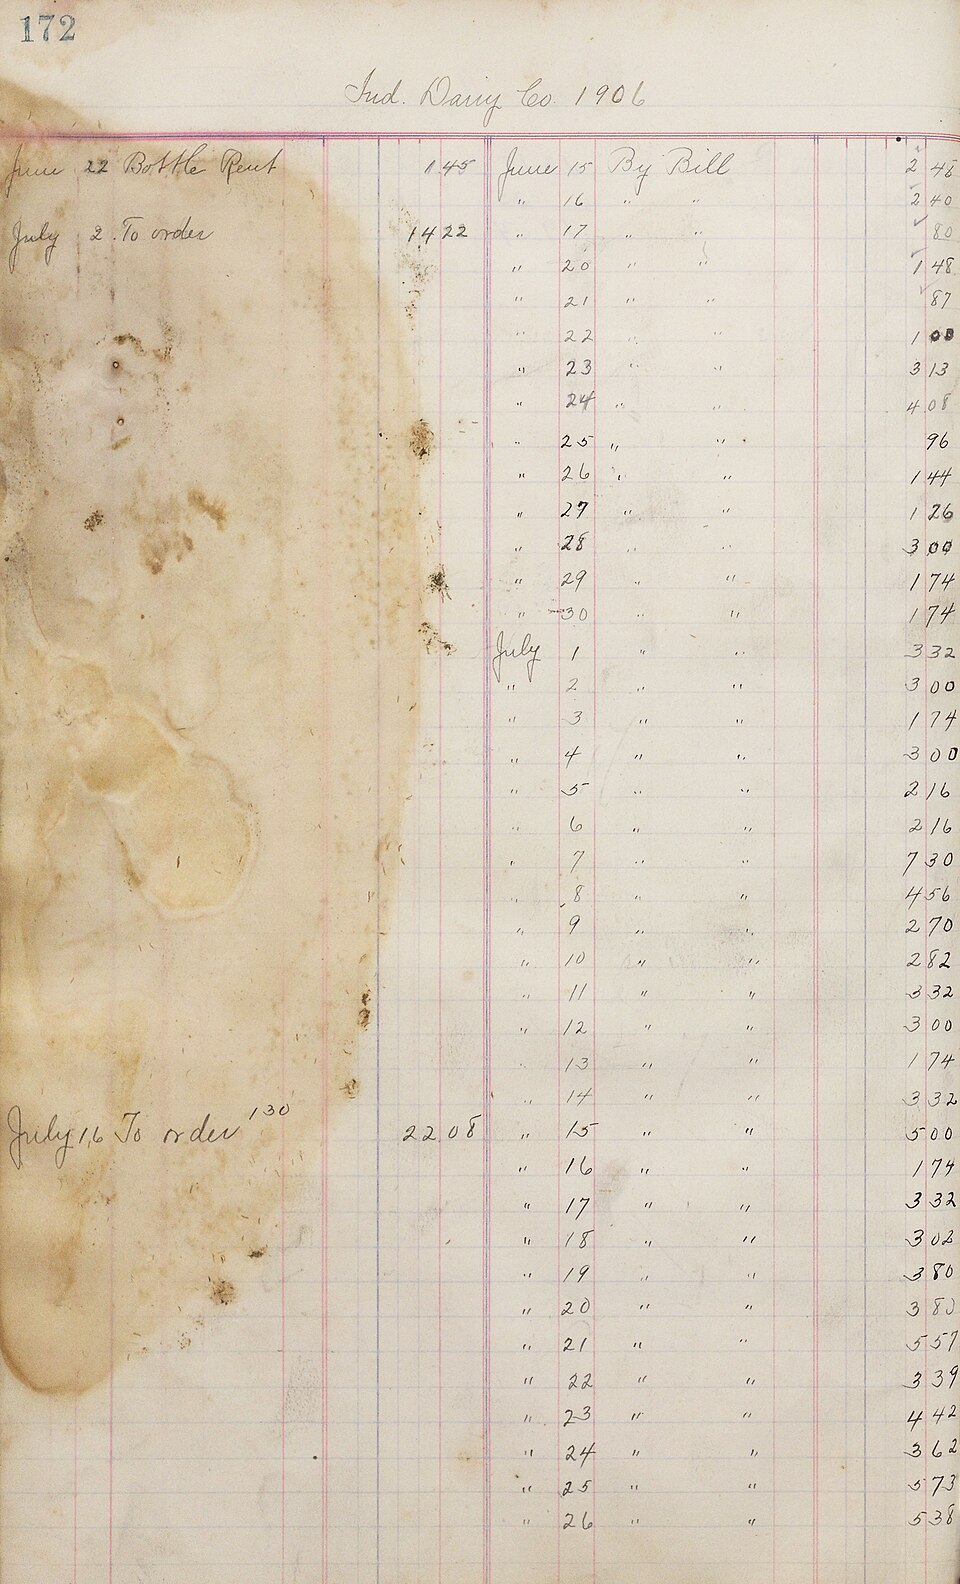 A ledger page with travel agency entries (commission, advances, refunds). (Image: Public domain, via Wikimedia Commons)
Based on the TU BTTM syllabus for Tourism and Hospitality Accounting, unit 8.
Discussion
Loading…